A well-known chicken brand with long leases at accessible prices, in a tougher stretch for U.S. sales, and how to pick a strong operator, from a NNN buyer’s broker with 225+ transactions.
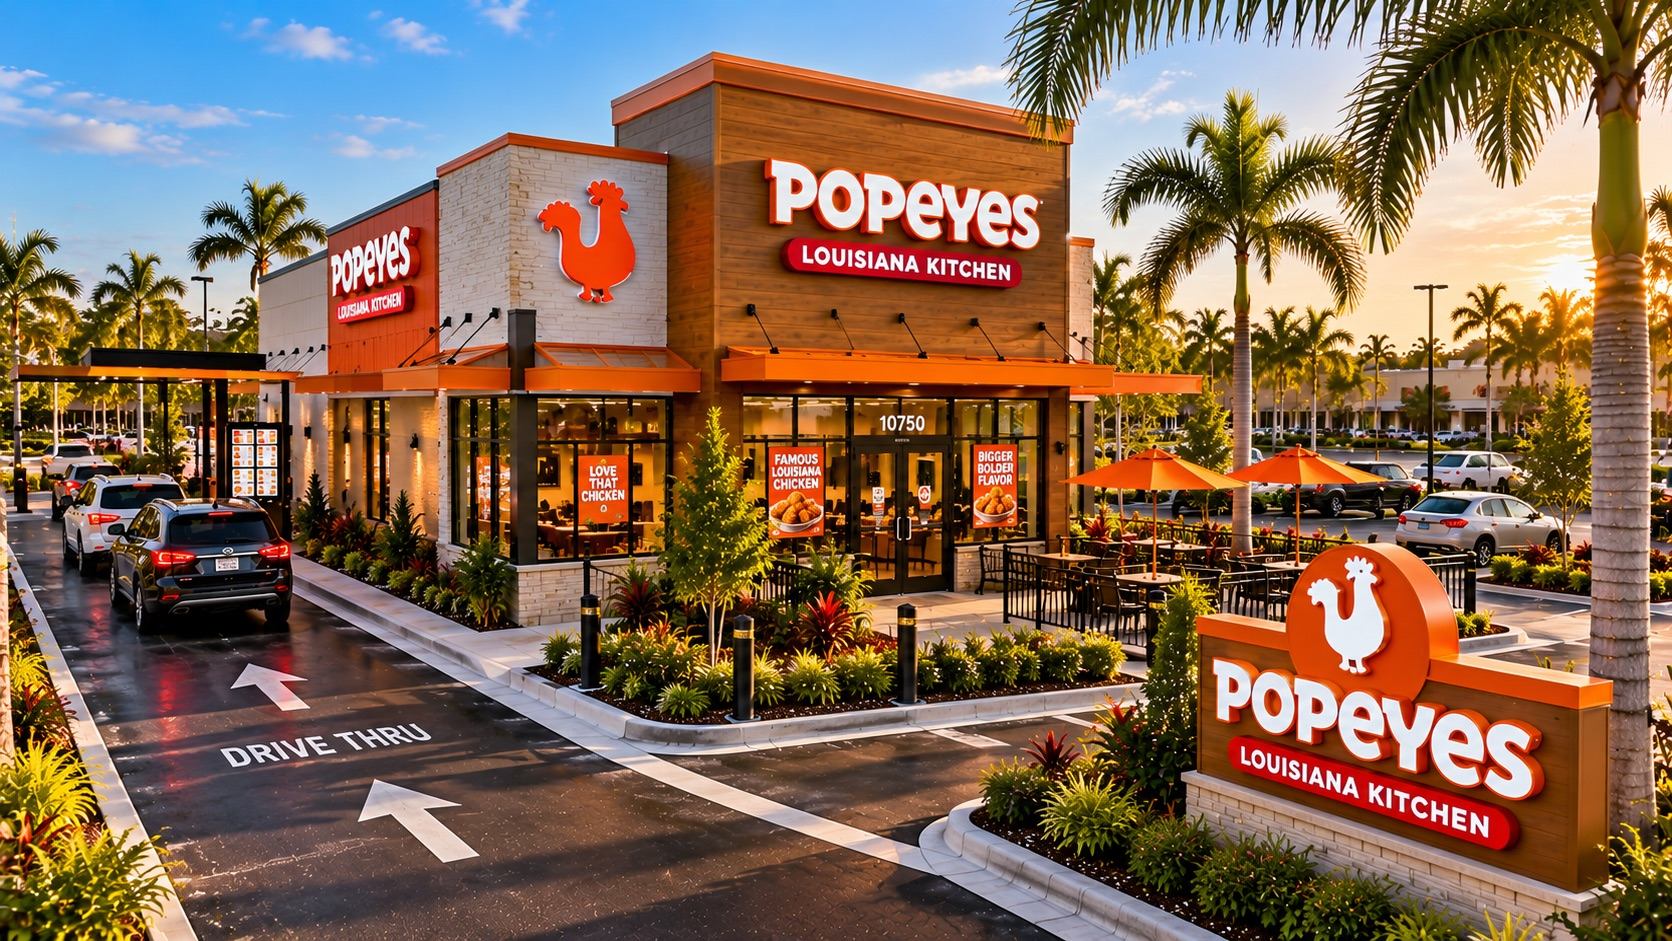
A Popeyes NNN property is a freestanding quick-service restaurant, often only about 2,000 square feet with a drive-thru on roughly two-thirds of an acre, leased on a long-term absolute NNN lease. New deals typically run 20 years with 10% rent increases every five years. Popeyes is owned by Restaurant Brands International (NYSE: QSR), also the parent of Burger King and Tim Hortons, rated BB+ by S&P.
Nearly all Popeyes are run by franchisees, so the lease is usually backed by the operator, not RBI. U.S. same-store sales have been falling, down 5.2% in Q2 2026, and a large Florida and Georgia franchisee, Sailormen, filed for bankruptcy in January 2026 and closed dozens of stores. That makes the operator and the individual store the heart of any Popeyes purchase on a 1031 exchange. Solid Investments FL helps buyers vet both, and our buyer representation is always free to you.
| Tenant | Usually a franchisee operating company, sometimes with a personal guarantee; corporate leases are rare. Confirm the tenant and every guarantor |
|---|---|
| Parent company | Restaurant Brands International (NYSE: QSR); U.S. office in Miami, Florida |
| Parent credit | RBI: S&P BB+, below investment grade; franchisee credit varies by operator |
| Restaurants | 5,468 worldwide, about 3,540 in the U.S. and Canada (June 2026) |
| Recent U.S. performance | Same-store sales down 5.2% in Q2 2026 |
| Building size | Often about 2,000 SF with a drive-thru |
| Typical lease term | 20 years on new leases |
| Lease type | Absolute NNN; fee-simple and ground-lease deals both trade |
| Rent increases | Typically 10% every 5 years |
| Typical cap rate (2026) | About 5.25%–6.25%, depending on the operator and the store |
| Typical price range | About $1M–$2.5M |
Restaurant counts and sales from Restaurant Brands International reports as of Q2 2026. Cap rates and pricing reflect current market conditions and vary by deal.
Most Popeyes leases are guaranteed by a franchisee, not RBI. Read exactly who signs the lease and who guarantees it, including any personal guarantee.
Some Popeyes deals are ground leases, where you own the land and the tenant owns the building. The main drawback is that you can’t depreciate the building. The upsides: the tenant paid to build the store, so it has a strong vested interest in staying; ground rents are typically at or below market; and in most ground leases the building reverts to you when the tenant vacates or the lease ends (verify it in your lease). That’s why ground leases usually trade at lower cap rates.
Confirm how many units actually back the lease. Franchisees often hold restaurants in separate subsidiaries, so a large operator’s lease may be guaranteed by an entity with only a few stores.
The 2026 Sailormen bankruptcy is a reminder that even big franchisees can fail. Ask for the operator’s financials and check for recent closures or bankruptcies.
With U.S. sales down, make sure your store is a keeper. Rent at 6%–8% of sales is healthy, below 6% is very strong, and around 10% is close to break-even.
On a 2,000-SF building, compare the rent per square foot to what similar restaurants lease for nearby. Rent at or below market makes the site easier to re-lease.
Corner sites with strong traffic, easy access and good drive-thru stacking hold value whoever the tenant is, and appeal to the many chicken brands still expanding.
Solid Investments FL is a NNN buyer's brokerage based in Lakewood Ranch (Sarasota), FL, with 225+ NNN transactions. We help investors and 1031 exchange buyers find, underwrite and close Popeyes and other quick-service restaurant properties nationwide, and our buyer representation is free.
As of 2026, Popeyes NNN properties generally trade around 5.25% to 6.25% cap rates. Strong multi-unit operators and new 20-year leases trade at the lower end, while smaller operators and shorter terms trade higher.
Almost always franchisee. Restaurant Brands International franchises nearly all of its restaurants, so the lease is usually guaranteed by the operator's company, sometimes with a personal guarantee. Always confirm exactly who signs and how many units back the guarantee.
Popeyes' parent, Restaurant Brands International, is rated BB+ by S&P, below investment grade. Franchisee operators are typically not rated, so their strength has to be judged from their size, financials and track record.
Yes, in the U.S. for now. Popeyes U.S. same-store sales fell 5.2% in Q2 2026, and the large franchisee Sailormen filed for bankruptcy in January 2026 and closed dozens of Florida and Georgia stores. Store-level sales and the operator's strength matter more than ever.
Start with how many restaurants actually back the guarantee, since franchisees often hold stores in separate subsidiaries. Next, compare rent to store sales: rent at 6% to 8% of sales is healthy, below 6% is very strong, and around 10% is close to break-even for many operators. Finally, check rent per square foot against the local market.
General information only, not investment, tax or legal advice. Credit ratings and market data change; verify current figures before investing.
We’ll help you find a strong operator and read the lease. Tell us your budget and timeline; our buyer representation is completely free.
📞 954-296-6955 | 11015 Gatewood Dr Suite 102, Lakewood Ranch, FL 34211